For high-income Canadians, incorporated professionals, and successful business owners, building and preserving wealth means navigating a punishing tax environment. Securing permanent life insurance for estate taxes, succession planning, or buy-sell agreements is often essential—yet committing six-figure annual premiums can feel like locking away productive capital.
An Immediate Financing Arrangement (IFA) is engineered to solve this exact trade-off.
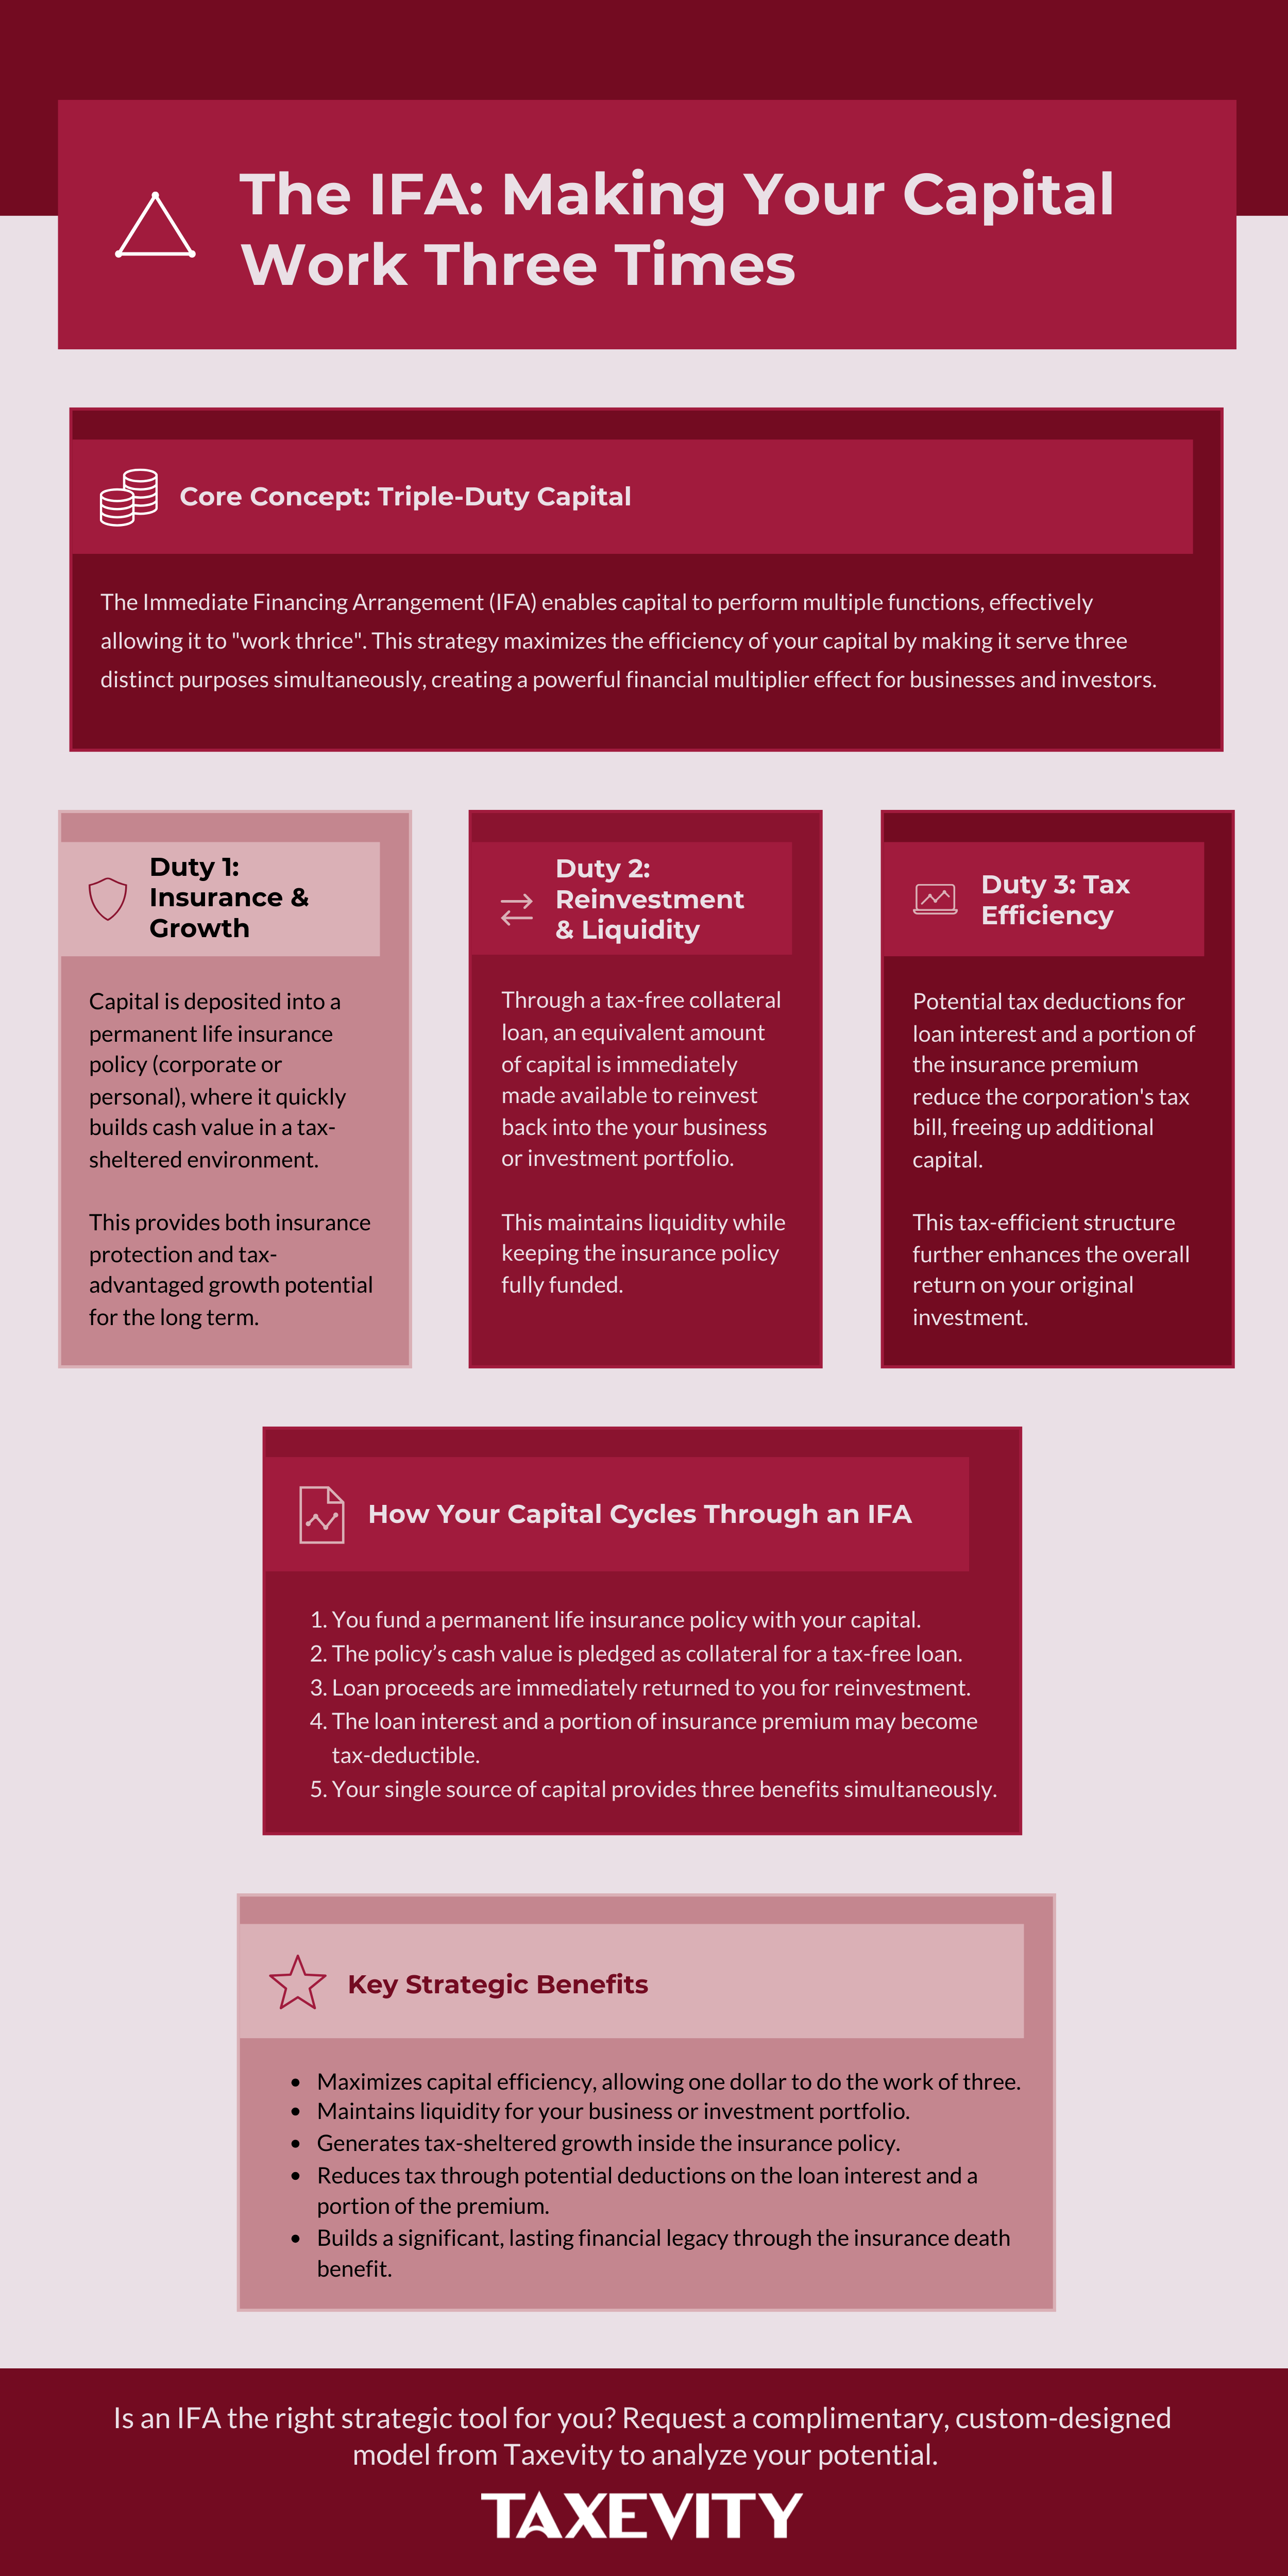
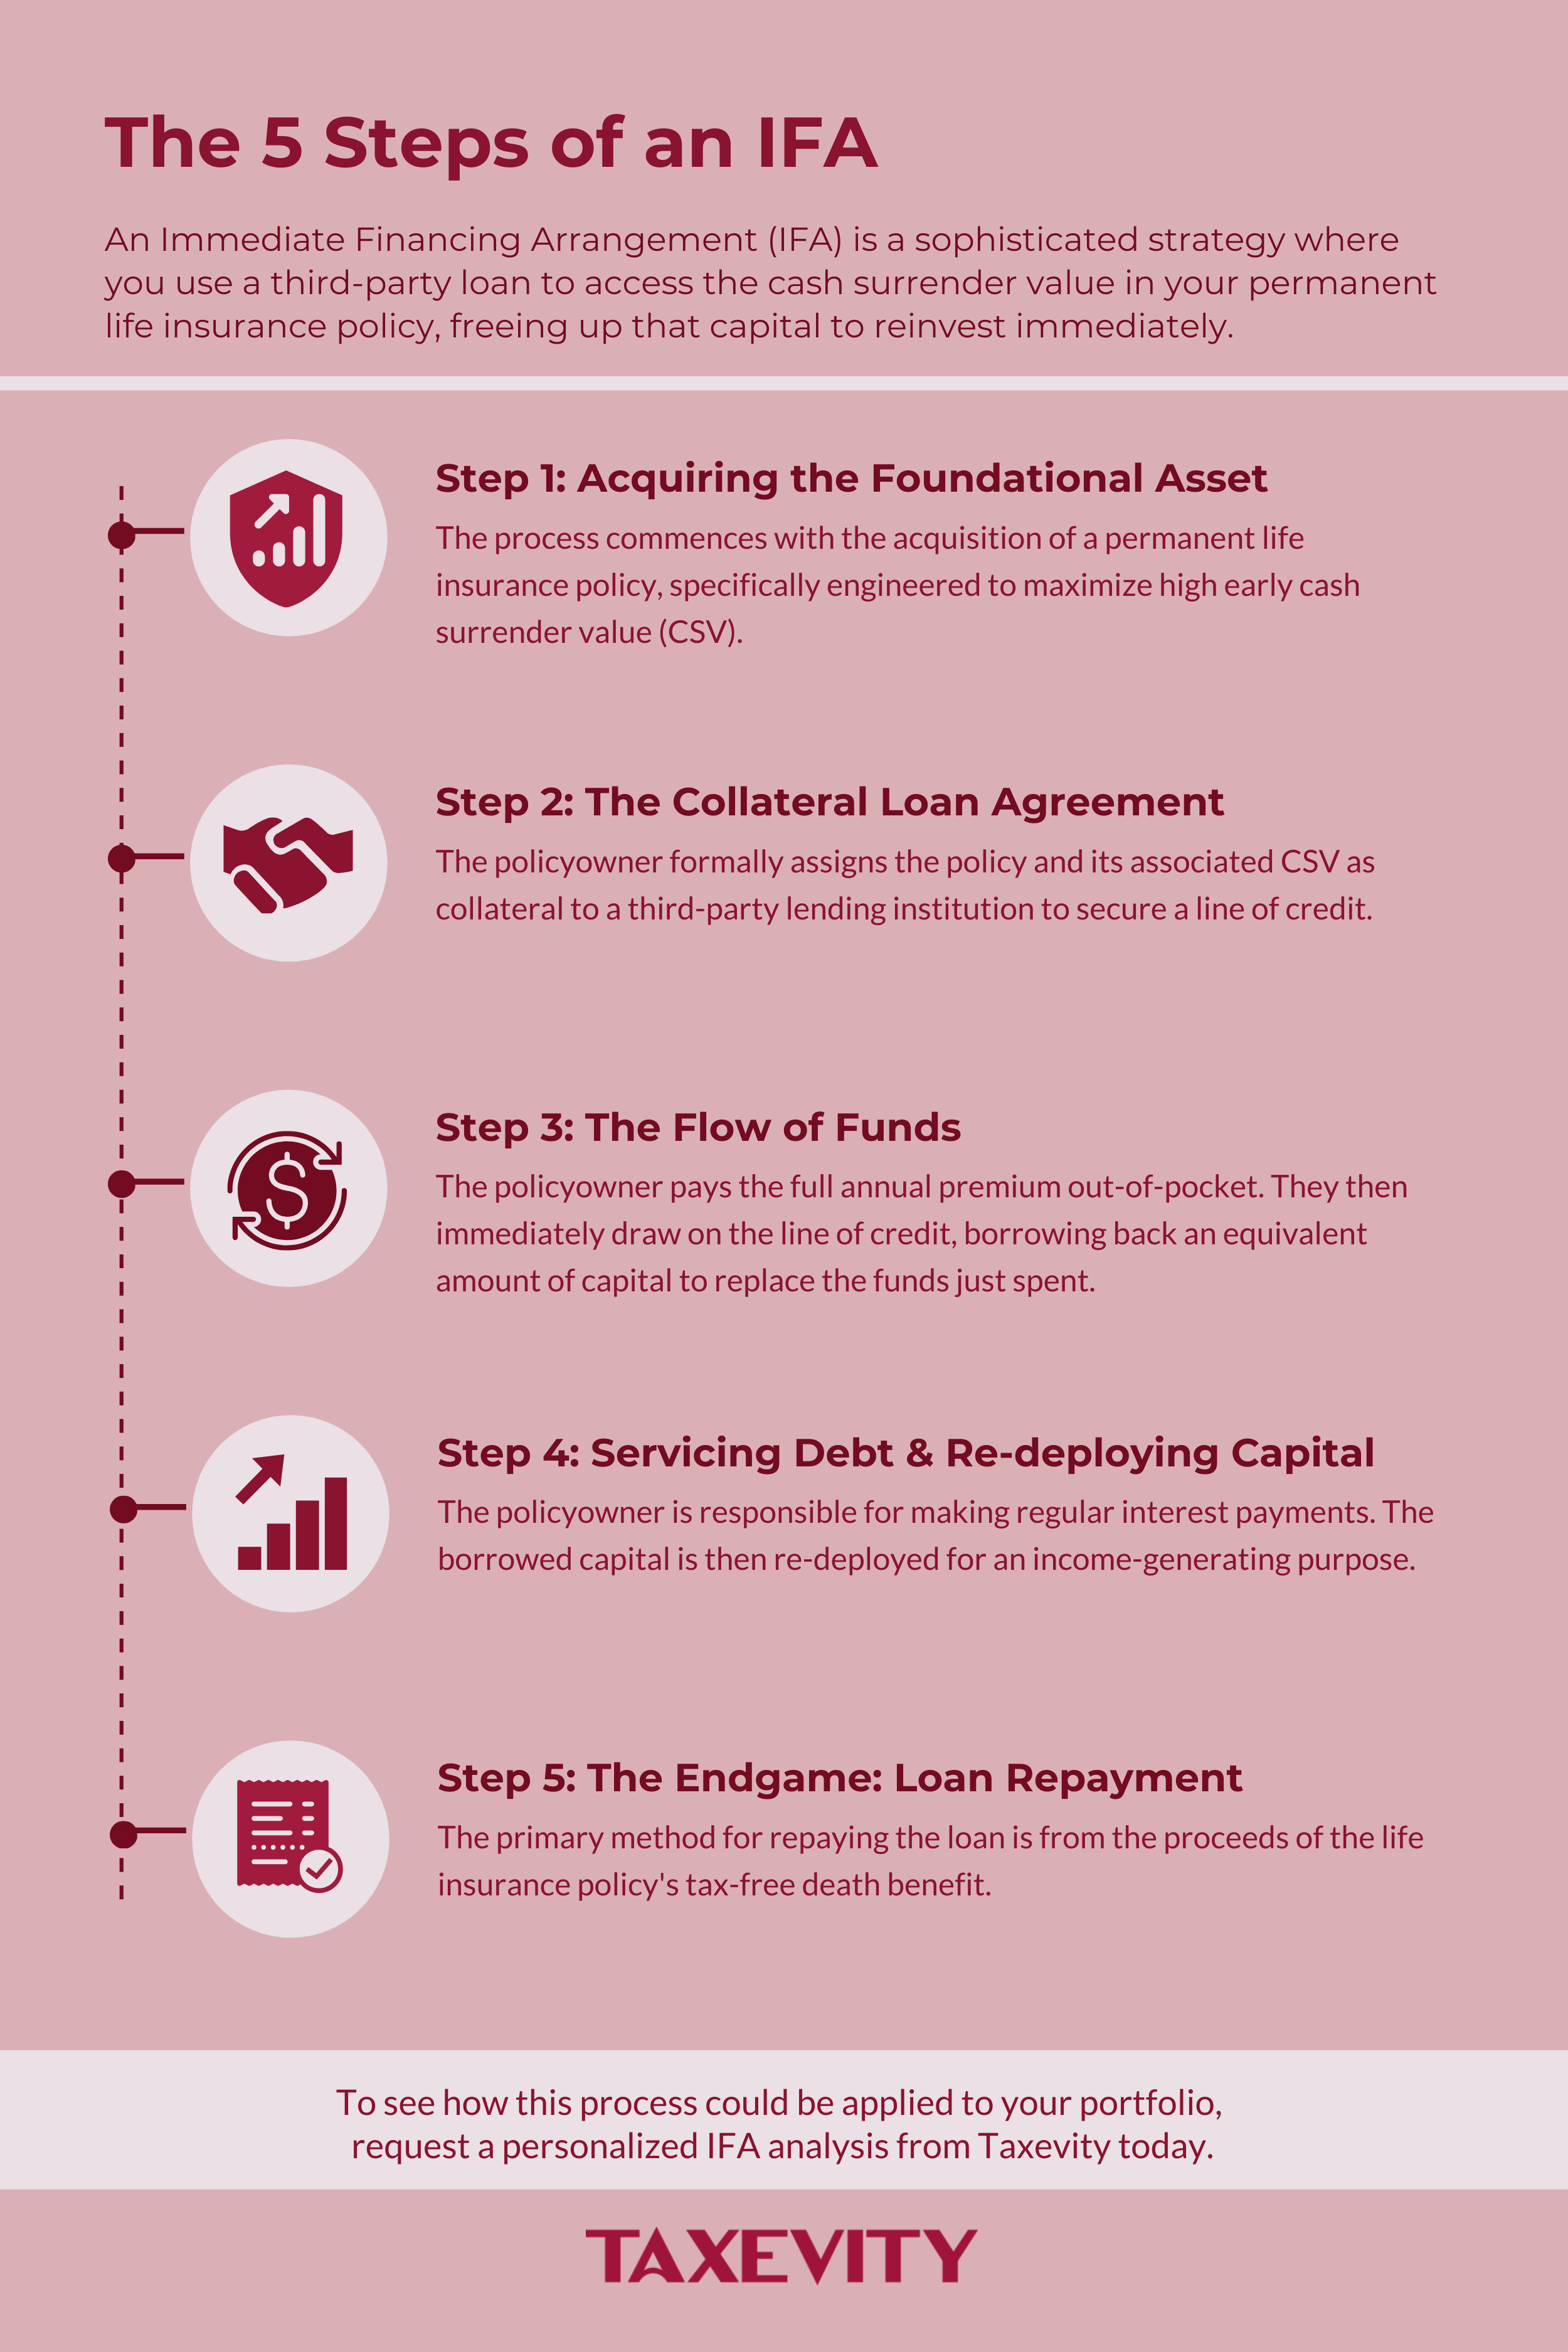
How the 5-Step IFA Architecture Works
An IFA is a contractual arrangement between three distinct parties: you (or your corporation), a Canadian life insurance company, and a third-party Schedule 1 bank or specialized lender.
- Acquire a High-Early-Cash-Value Whole Life Policy: Your corporation (or you personally) purchases a participating whole life policy engineered to maximize early Cash Surrender Value (CSV) using non-borrowed funds.
- Assign the Policy as Collateral: The policy is pledged to a third-party Canadian financial institution via a formal collateral assignment agreement.
- Draw the Collateral Line of Credit: Because guaranteed whole life CSV is institutional-grade collateral, lenders advance up to 100% of the CSV (or up to 100% of the premium paid when supported by additional temporary security).
- Redeploy Borrowed Funds for an Income-Earning Purpose: The loan proceeds are invested in a traceable, income-producing portfolio or active business operation.
- Settle the Loan at Death & Unlock the CDA: Upon death, the tax-free insurance proceeds pay off the bank loan, and the net death benefit (plus the loan amount) credits the corporation’s Capital Dividend Account (CDA).
The Four Core Tax Advantages of a Properly Structured IFA
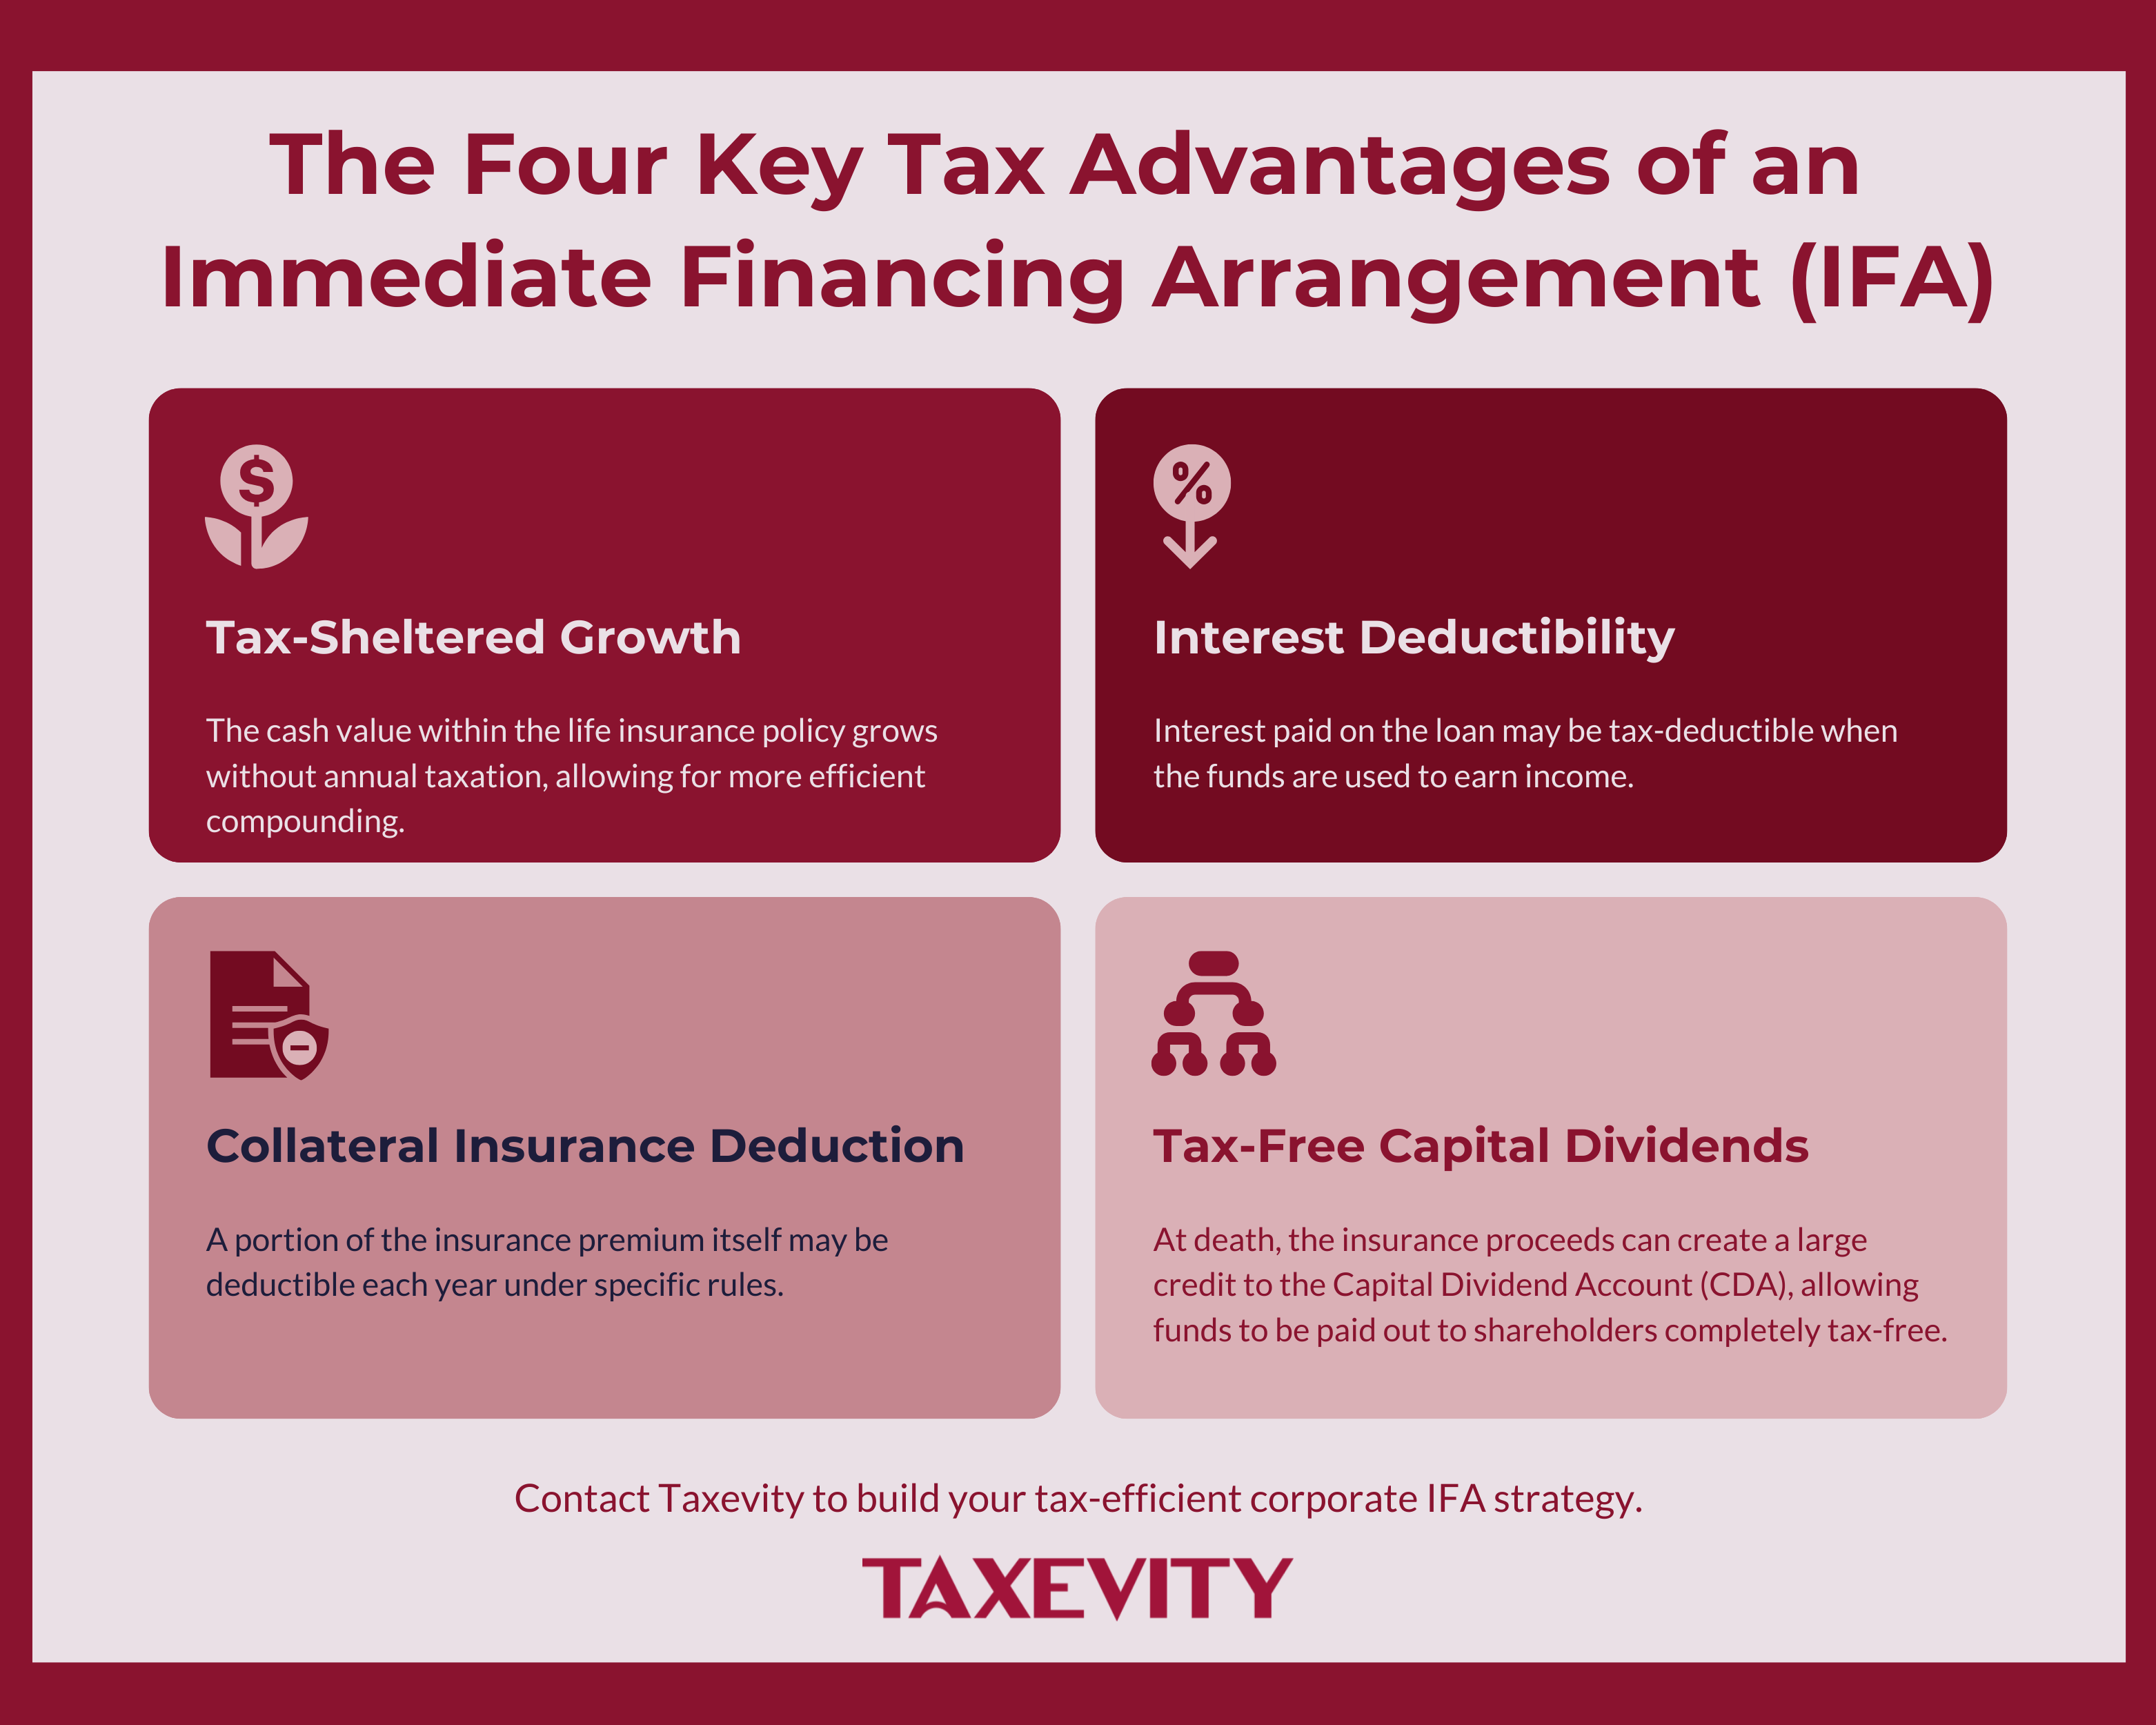
- Tax-Sheltered Cash Value Growth: Growth inside an exempt participating whole life policy is not subject to annual corporate passive investment tax (~50.17% in Ontario) and does not grind down your Small Business Deduction (SBD).
- Interest Deductibility (
ITA 20(1)(c)): When borrowed funds are directly traced to an eligible investment with a reasonable expectation of income, the loan interest is generally tax-deductible. - Collateral Insurance Deduction (
ITA 20(1)(e.2)): Where a policy is required as collateral for an eligible loan from a restricted financial institution, a portion of the policy’s Net Cost of Pure Insurance (NCPI) may also be deductible. - Surplus CDA Capacity at Death: Because the Capital Dividend Account credit is calculated on the gross death benefit minus the policy’s Adjusted Cost Basis (ACB), repaying the loan still leaves a massive surplus CDA balance that can unlock other trapped corporate retained earnings tax-free.